



















Rwanda VAT 2026: Complete Guide to VAT Registration, Rates, EBM & Compliance
Complete Rwanda VAT guide for 2026 covering registration thresholds, 18% VAT, voluntary registration, EBM, invoices, filing, exemptions, penalties and compliance.

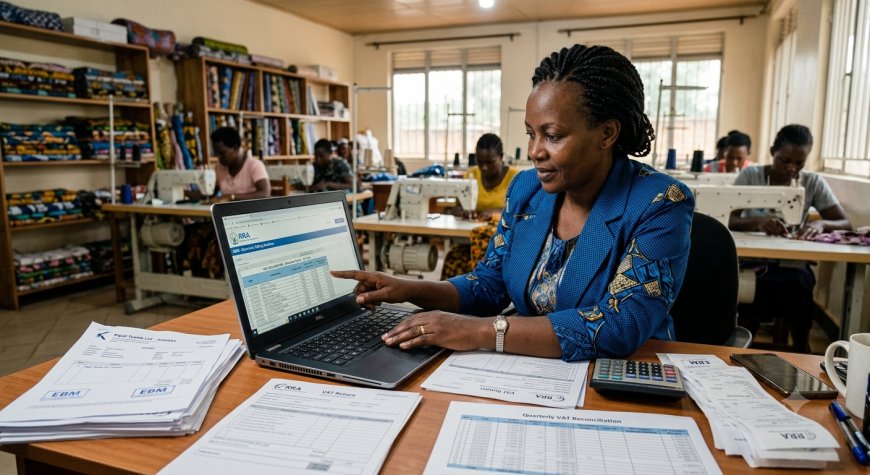
Rwanda VAT 2026: Complete Guide to VAT Registration, Rates, EBM & Compliance
Value Added Tax, commonly called VAT, is one of the most important taxes for businesses operating in Rwanda. It affects how businesses price goods and services, issue invoices, record sales, use electronic invoicing systems, file tax returns and account for tax collected from customers.
For a small business owner, reaching the VAT registration threshold can change the way the business operates. For an established company, VAT compliance becomes part of the normal monthly or quarterly tax routine. And for businesses supplying larger companies or competing for public tenders, VAT registration can also affect how customers evaluate the business.
This guide explains how VAT works in Rwanda in 2026, including who must register, the turnover thresholds, the standard VAT rate, voluntary registration, electronic invoicing, filing obligations, VAT-exempt transactions, common compliance mistakes and what to do when your business crosses the registration threshold.
What Is VAT in Rwanda?
VAT is a consumption tax charged on taxable goods and services. Although businesses collect VAT from customers, the tax is ultimately connected to consumption rather than being a direct tax on business profit.
A VAT-registered business generally charges VAT on taxable sales, records VAT paid on eligible business purchases and accounts to the tax administration for the difference according to the applicable rules.
This distinction is important because VAT should not simply be treated as additional business income. A business collecting VAT needs to maintain proper records and account for the tax through the required VAT return process.
What Is the VAT Rate in Rwanda?
The standard VAT rate in Rwanda is 18% for taxable supplies subject to the standard rate.
However, not every transaction is treated in exactly the same way. Depending on the goods or services involved, a transaction may be taxable at the standard rate, zero-rated or exempt.
| Treatment | Meaning |
|---|---|
| Standard-rated | VAT is normally charged at the standard rate. |
| Zero-rated | The applicable VAT rate is 0%, while the transaction remains within the VAT framework. |
| Exempt | VAT is not charged on supplies classified as exempt under the applicable rules. |
For example, RRA's VAT materials identify certain exported goods and services as zero-rated and list categories such as books, newspapers and journals among exempt supplies. The exact treatment depends on the transaction and applicable tax rules.
Who Must Register for VAT in Rwanda?
The most important issue for many businesses is the turnover threshold.
According to the Rwanda Revenue Authority, mandatory VAT registration applies when a taxpayer's turnover:
- Exceeds RWF 20 million during a 12-month period; or
- Exceeds RWF 5 million in three consecutive months.
When the applicable threshold is reached, the taxpayer must register within the period prescribed by RRA. RRA currently states that registration should be completed within seven days from the end of the relevant year or three-month period.
Example: When Does a Small Business Cross the VAT Threshold?
Consider a small electronics business whose taxable turnover grows steadily during the year.
If the business eventually exceeds RWF 20 million in the relevant 12-month period, it cannot simply continue operating as a non-VAT taxpayer because its turnover has passed the mandatory registration threshold.
Likewise, the three-month threshold matters independently. A business may need to consider VAT registration even when its full-year turnover has not yet reached RWF 20 million if its turnover exceeds RWF 5 million in three consecutive months.
Can a Business Register for VAT Voluntarily?
Yes. A business does not necessarily have to wait until it crosses the mandatory threshold.
RRA allows voluntary VAT registration for taxpayers that do not meet the mandatory turnover threshold, subject to the applicable requirements.
Voluntary registration can make sense in some situations, particularly where a business works with VAT-registered customers, wants to operate within a more formal tax structure or expects to grow rapidly.
However, voluntary registration also creates additional compliance responsibilities. A business should therefore consider the administrative cost, invoicing requirements, accounting system and customer base before deciding to register voluntarily.
Should a Small Business Register for VAT Before Reaching the Threshold?
There is no single answer for every business.
| Situation | What to consider |
|---|---|
| Mostly individual consumers | Adding VAT may affect the final price customers see. |
| Selling mainly to VAT-registered businesses | VAT registration may fit more naturally into business-to-business transactions. |
| Rapidly growing business | Early preparation can make the eventual transition easier. |
| Very small operation | The additional record-keeping and compliance requirements should be considered. |
The important point is that VAT registration should be a business decision based on the applicable rules and the company's operating model—not simply a way of making a business appear larger.
How to Register for VAT in Rwanda
VAT registration is connected to the taxpayer's registration and tax profile with the Rwanda Revenue Authority.
A business that is approaching or has crossed the threshold should first ensure that its taxpayer information is accurate and that the appropriate VAT registration process is completed.
Step 1: Confirm Your Turnover
Review your sales records and determine whether your business has crossed either of the mandatory VAT thresholds.
Do not rely only on money received in a bank account. Your accounting records should allow you to establish the turnover relevant to your tax obligations.
Step 2: Review the Nature of Your Supplies
Determine whether the goods or services you provide are taxable, zero-rated or exempt. This matters because turnover from exempt activities may be treated differently from taxable supplies for VAT purposes.
Step 3: Ensure Your Taxpayer Information Is Correct
Your business should have the appropriate taxpayer registration and TIN information. If your business was registered through the Rwanda business registration system, its tax registration is integrated with RRA processes.
Step 4: Request VAT Registration
VAT registration can be requested through the applicable RRA taxpayer services. RRA's tax guidance also provides for VAT registration during business registration where the relevant information is supplied.
Step 5: Prepare Your Invoicing System
VAT registration is not just about receiving a VAT certificate. Your business must also be capable of issuing compliant invoices and maintaining the required transaction records.
What Happens After VAT Registration?
Once registered, the business takes on additional VAT responsibilities.
RRA identifies several important obligations for VAT-registered taxpayers, including:
- Displaying the VAT registration certificate as required.
- Issuing electronic invoices through the required electronic invoicing system.
- Keeping appropriate transaction and accounting records.
- Submitting VAT returns according to the applicable filing frequency.
- Using an Electronic Billing Machine where required.
- Making payments of VAT due within the prescribed deadlines.
What Is EBM and Why Does It Matter for VAT?
EBM means Electronic Billing Machine. It is an important part of Rwanda's tax administration system for businesses that are required to issue electronic tax invoices.
For a VAT-registered business, VAT compliance therefore goes beyond calculating 18% on a calculator. Sales need to be properly recorded and invoiced through the applicable electronic system.
This is particularly important for businesses that have many daily transactions. A weak invoicing system can make it difficult to reconcile sales, purchases, VAT collected and VAT reported to RRA.
How Is VAT Calculated?
A simplified example can help explain the basic concept.
Suppose a business makes a taxable sale worth RWF 100,000 before VAT.
At an 18% VAT rate:
- Price before VAT: RWF 100,000
- VAT: RWF 18,000
- Total customer price: RWF 118,000
The example is intentionally simplified. Actual VAT accounting can involve input VAT, output VAT, exempt supplies, zero-rated supplies, adjustments and other rules.
Output VAT vs Input VAT
One of the most important concepts for a VAT-registered business is the difference between output VAT and input VAT.
Output VAT
Output VAT is VAT charged on taxable sales made by the business.
Input VAT
Input VAT generally refers to VAT incurred on eligible business purchases and expenses, subject to the applicable rules and documentation requirements.
The relationship between these amounts is important when preparing the VAT return.
How Often Must VAT Returns Be Filed?
VAT filing frequency depends on the taxpayer's circumstances and applicable turnover rules.
RRA currently states that a taxpayer whose annual turnover is RWF 200 million or less declares VAT quarterly, while a taxpayer whose annual turnover is more than RWF 200 million declares VAT monthly.
RRA's current guidance states that the VAT return is filed within 15 days following the end of the relevant filing period.
| Annual turnover | VAT filing frequency |
|---|---|
| RWF 200 million or less | Quarterly |
| More than RWF 200 million | Monthly |
What Records Should a VAT-Registered Business Keep?
A serious VAT system begins with good records.
Businesses should maintain records that allow them to reconcile:
- Sales invoices
- Purchase invoices
- Electronic invoices
- VAT charged to customers
- Eligible VAT incurred on purchases
- Bank and mobile-money transactions
- Credit notes and adjustments
- VAT returns submitted to RRA
- Payments made to RRA
The goal is to make it possible to explain how the figures reported in a VAT return were produced.
VAT Exemptions vs Zero-Rated VAT: What Is the Difference?
This is an area where many small businesses become confused.
Zero-rated does not mean exactly the same thing as VAT-exempt.
With a zero-rated supply, the applicable VAT rate is 0%. The transaction remains within the VAT system.
An exempt supply, on the other hand, is treated as exempt under the VAT rules.
This distinction can affect how a business handles input VAT and therefore should not be ignored when preparing accounts.
What Happens If You Cross the VAT Threshold and Do Not Register?
Crossing a VAT threshold is not something a business should treat as an informal milestone.
Once the legal registration obligation arises, the business needs to take the required action within the prescribed period. RRA's registration guidance also makes clear that taxpayers have obligations to file and pay registered taxes on time.
Continuing to operate without addressing the VAT obligation can create compliance problems, including tax liabilities and potential penalties or interest under the applicable rules.
Common VAT Mistakes Made by Small Businesses in Rwanda
1. Watching Only Annual Turnover
Some businesses monitor yearly sales but forget that the VAT rules also use a three-consecutive-month threshold.
2. Treating VAT as Profit
VAT collected from customers should not automatically be treated as money available for business spending.
3. Mixing Personal and Business Transactions
When personal and business payments are mixed together, reconciling sales and purchases becomes significantly harder.
4. Poor Invoice Records
Missing invoices and incomplete electronic records can make it difficult to support VAT figures during reconciliation or an RRA review.
5. Assuming Every Purchase Creates Recoverable VAT
Input VAT treatment depends on the applicable tax rules and documentation. A business should not assume that every expense automatically creates an amount that can be deducted.
6. Registering for VAT Without Preparing the Accounting System
A company may obtain VAT registration but still struggle because its accounting, invoicing and record-keeping processes are not ready.
VAT and Public Tenders in Rwanda
VAT can also become relevant when a business participates in formal procurement.
RRA's VAT materials identify voluntary VAT registration as potentially beneficial for businesses seeking to bid on public tenders. This does not mean VAT registration guarantees a tender, but it demonstrates why tax status can become commercially important as a business grows.
Businesses planning to supply government institutions or large companies should therefore consider tax compliance as part of their wider business infrastructure rather than treating it as paperwork completed only when requested.
VAT for Online Businesses and Digital Businesses
The growth of online commerce means that some entrepreneurs may assume VAT is relevant only to physical shops. That is not necessarily the case.
An online business selling taxable goods or services in Rwanda should evaluate its tax registration obligations in the same way as a traditional business.
This includes businesses operating through:
- Online stores
- Social media shops
- Digital service businesses
- Consulting businesses
- Technology companies
- Professional service businesses
- Other commercial platforms
The important questions are the nature of the supply, the taxpayer's turnover and the applicable tax rules—not whether customers found the business through Instagram, WhatsApp, a website or a physical shop.
How Businesses Can Prepare Before Reaching the VAT Threshold
The best time to prepare for VAT is before the business is forced to react to the threshold.
- Track monthly turnover. Do not wait until the end of the year to calculate sales.
- Monitor the three-month threshold. This can trigger VAT registration before the annual threshold becomes the main issue.
- Separate business finances. Use proper business accounts and transaction records.
- Organize invoices. Keep sales and purchase documentation systematically.
- Understand your products. Identify taxable, zero-rated and exempt supplies.
- Prepare your accounting system. Make sure VAT can be reconciled with sales and purchases.
- Learn the EBM/electronic invoicing requirements. Do this before registration becomes urgent.
- Monitor RRA announcements. Tax procedures and administrative requirements can change.
Rwanda VAT Compliance Checklist for Businesses
| Task | Check |
|---|---|
| Monitor turnover | ☐ |
| Check VAT threshold | ☐ |
| Confirm taxable supplies | ☐ |
| Complete VAT registration when required | ☐ |
| Set up compliant electronic invoicing | ☐ |
| Maintain sales and purchase records | ☐ |
| Reconcile input and output VAT | ☐ |
| File VAT returns on time | ☐ |
| Pay VAT due on time | ☐ |
Frequently Asked Questions About VAT in Rwanda
What is the VAT rate in Rwanda in 2026?
The standard VAT rate in Rwanda is 18% for supplies subject to the standard rate.
How much turnover requires VAT registration in Rwanda?
Mandatory registration generally applies when turnover exceeds RWF 20 million over 12 months or RWF 5 million in three consecutive months, subject to the applicable rules.
Can I register for VAT before reaching the threshold?
Yes. RRA provides for voluntary VAT registration, subject to the applicable requirements.
Do all businesses have to charge 18% VAT?
No. The VAT treatment depends on the nature of the supply. Some transactions may be standard-rated, zero-rated or exempt.
How often do I file VAT returns?
RRA currently states that taxpayers with annual turnover of RWF 200 million or less file VAT returns quarterly, while those above RWF 200 million file monthly.
Does a VAT-registered business need EBM?
VAT-registered businesses are subject to electronic invoicing requirements, including use of an Electronic Billing Machine where applicable.
Can an online business in Rwanda be required to register for VAT?
Yes. Operating online does not by itself remove a business from Rwanda's tax obligations. The business should assess its activities, turnover and applicable VAT rules.
What happens if my business crosses the VAT threshold?
You should review the registration obligation immediately and complete the required VAT registration within the applicable statutory period rather than waiting until the next tax year.
Final Takeaway
VAT becomes increasingly important as a Rwandan business grows. The key is not simply knowing that the standard rate is 18%. Business owners need to understand when registration becomes mandatory, how the RWF 20 million and RWF 5 million thresholds work, what voluntary registration means, how electronic invoicing fits into compliance and how VAT returns must be filed.
For a growing business, the smartest approach is to monitor turnover continuously and build proper accounting and invoicing systems before the VAT threshold is reached. That makes the transition far easier than discovering the obligation after the business has already crossed the threshold.
Always confirm the latest requirements with the Rwanda Revenue Authority before making tax decisions, particularly where your business has complex transactions, exempt supplies, imports, exports or significant input VAT.
Official Sources
- Rwanda Revenue Authority — VAT registration and VAT taxpayer obligations
- Rwanda Revenue Authority — VAT filing and declaration guidance
- Rwanda Revenue Authority — Tax Handbook
What's Your Reaction?
 Like
0
 Dislike
0
 Love
0
 Funny
0
 Angry
0
 Sad
0
 Wow
0